SOX 404 Testing Walkthrough: From Walkthroughs and Sampling to Remediation in 2026
Why SOX 404 Still Drives Audit Fees
SOX 404 is where closings meet opinions. A clean Month-End Close with weak control evidence still produces comments, deficiencies, and higher fees.
This guide gives controllers and pre-IPO teams a repeatable testing workflow that aligns with COSO, Internal Controls Framework, and Audit Procedures.
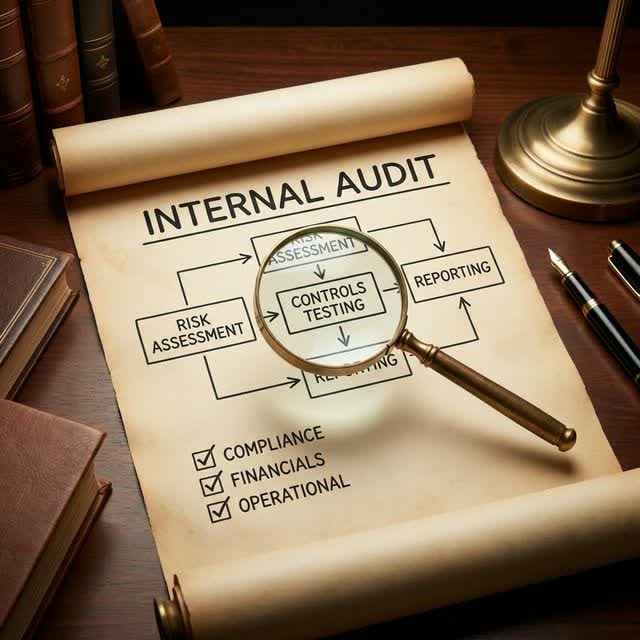
Program Architecture
| Phase | Output | Owner |
|---|---|---|
| Scoping | In-scope accounts, assertions, locations | Controller + auditor |
| Documentation | Flowcharts, risk-control matrices | Process owners |
| Walkthroughs | Design effectiveness conclusion | Management tester |
| Operating testing | Sample results + exceptions | Management tester |
| Aggregation | Deficiency severity memo | Controller + CFO |
| Remediation | Remediation test + close memo | Owner + retest |
| Reporting | Management assessment, disclosure | CFO + audit committee |
Link scoping to Financial Statement Analysis materiality and to Enterprise Risk Management.
1. Scoping: Accounts, Assertions, Risks
Start from materiality, not control count.
- List significant accounts by quantitative + qualitative risk (revenue, payroll, leases, equity, tax).
- Map assertions: existence, completeness, valuation, rights, presentation.
- Identify entity-level controls first — they reduce transactional testing.
- Document out-of-scope rationale; auditors challenge scope cuts.
For revenue, tie to ASC 606. For leases, tie to ASC 842. For inventory, tie to Inventory FIFO/LIFO.
2. Walkthroughs: Prove Design
A walkthrough traces one transaction end-to-end with the actual performer.
Script:
- Ask performer to show, not tell. Follow the ticket, approval, posting, and rec.
- Confirm IT dependencies: who has access, what report logic, what exception handling.
- Capture evidence: screenshots, report parameters, approval timestamps.
- Conclude on design: would this prevent or detect material error if operated?
Common design gaps: approver without competence, detective review without precision thresholds, automated report nobody validates.
3. Sampling: How Much Is Enough
| Frequency | Typical management sample | Notes |
|---|---|---|
| Annual | 1 | Re-perform full control |
| Quarterly | 2-4 | Cover all quarters |
| Monthly | 2-6 | Vary preparers if rotated |
| Weekly | 5-15 | Focus on high-risk weeks (close) |
| Daily / per-transaction | 15-30+ | Use data analytics where possible |
Rules:
- Test operation, not just existence of a signature. Re-perform calculation, tie support.
- For management review controls, test precision: threshold, criteria, follow-up.
- Document deviations immediately; don’t replace samples to hide failures.
For payroll, tie samples to Payroll Tax Guide. For AP, tie to Automating AP with AI logs.
4. IT General Controls and Reports
Most SOX failures are IT failures:
- Logical access: joiner/mover/leaver, admin rights, quarterly reviews.
- Change management: approval, testing, migration for finance apps.
- Report logic: validate completeness/accuracy of key reports (IPE).
- Segregation in-system: enforce the matrix from QuickBooks vs Xero Controls.
If you use Bookkeeping Software, export audit logs and lock-date reports as IPE and test them.
5. Deficiency Aggregation and Severity
Rate each exception, then aggregate by account and assertion.
| Level | Test | Action |
|---|---|---|
| Deficiency | Control failed but no reasonable possibility of material error | Remediate, retest |
| Significant deficiency | Important to audit committee governance | Disclose to audit committee, remediate urgently |
| Material weakness | Reasonable possibility of material misstatement | Disclose publicly, adverse ICFR opinion, intensive remediation |
Consider compensating controls only if precisely designed and tested — vague manager review does not compensate.
Coordinate severity memos with the Audit Committee and Q1 Audit Prep.
6. Remediation That Actually Closes
Bad remediation: retrain and re-sign. Good remediation:
- Root cause: design vs operation vs competence vs evidence.
- Fix design: rewrite step, threshold, owner, or report logic.
- Operate for sufficient period, then retest with fresh samples.
- Update flowcharts and risk-control matrix same day.
Track in a deficiency log: ID, owner, due date, retest date, auditor concurrence.
Pre-IPO Fast Track
If heading to IPO — see IPO Process and IPO Readiness:
- Year -2: document + remediate design gaps.
- Year -1: full operating testing + auditor dry run.
- Year 0: management assessment + auditor opinion readiness, Audit Committee Charter staffed.
Budget for Fractional CFO or SOX consultant for first cycle; insource cycle two.
FAQ
How long does first-year SOX 404 take?
3-6 months for scoping through remediation for a single-entity filer; multi-entity or carve-outs take longer. Start walkthroughs at Q1, not Q4.
Can we rely on SOC 1 reports?
Only for outsourced controls with complementary user-entity controls tested. Read the bridge letter and test your side — see SOC 1 vs SOC 2.
What causes most material weaknesses?
Management review without precision, IT access failures, and revenue cut-off controls. All three are preventable with the checklists in Month-End Close.
Next Steps
- Freeze your scoping memo and RCM this month.
- Run walkthroughs for revenue, payroll, and close controls.
- Log deficiencies in one register and report severity to the audit committee quarterly.