Navigating Down Rounds in 2026: Anti-Dilution Provisions and Cap Table Impact
The Math Nobody Models Until It Hurts
Down rounds stopped being rare when valuations normalized. Yet most founders discover how anti-dilution works at the term-sheet stage of the round that triggers it — the worst possible classroom. The mechanics are deterministic: the only variables are which formula your charter contains, how much is raised, and who shows up with a check.
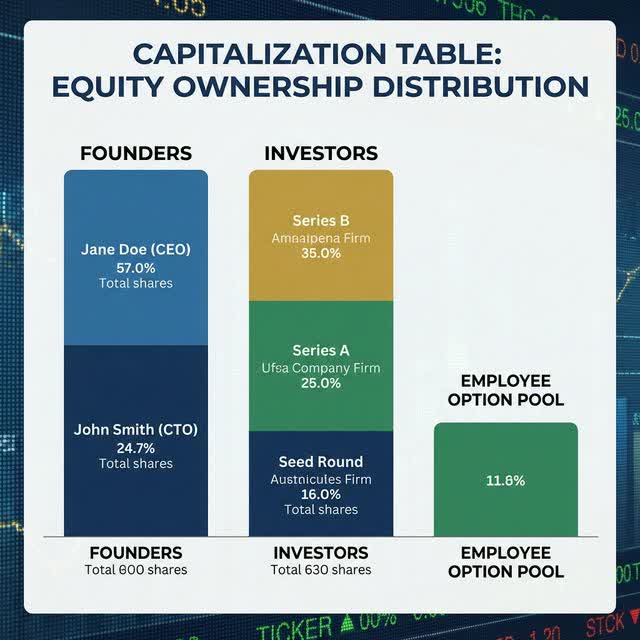
Setup for every example below: Series A raised $10M at $2.00/share (5M preferred shares). Fully diluted pre-money count is 8M shares (preferred + common + option pool). Now a Series B raises $5M at $1.00/share (5M new shares). Watch what each protection does to the same facts.
Pair with Series A Fundraising, Cap Table Management, Venture Capital Term Sheets, and Burn Rate and Runway.
Full Ratchet: The Cap-Table Nuke
The Series A conversion price resets from $2.00 all the way to $1.00 — regardless of the $5M raise size:
| Item | Math | Result |
|---|---|---|
| Series A conversion ratio | $2.00 / $1.00 | 1 preferred → 2 common |
| Series A as-converted | 5M × 2 | 10M common-equivalent shares |
| Founder/employee share | Was ~37% pre-round | Crushed toward ~20% (before new option pool top-ups) |
Full ratchet prices the entire prior round as if it had invested at the down-round price. One small bridge at a low valuation can double the preferred overhang and wipe out employee option value overnight. That is why full ratchets are rare in institutional venture deals — and why founders must check the charter before signing any bridge, since bridge notes often carry their own ratchet-like discounts and caps that compound the damage — see Venture Debt vs Bridge.
Broad-Based Weighted Average: The Proportional Alternative
The standard venture formulation softens the blow proportionally to round size. Formula:
CP2 = CP1 × (A + B) / (A + C)
- A = fully diluted shares outstanding (including options, warrants, convertibles — the “broad base”)
- B = shares that would have been issued at the old price for the new money ($5M ÷ $2.00 = 2.5M)
- C = shares actually issued (5M)
Applied:
| Step | Math | Value |
|---|---|---|
| A + B | 8.0M + 2.5M | 10.5M |
| A + C | 8.0M + 5.0M | 13.0M |
| New conversion price | $2.00 × 10.5 / 13.0 | $1.615 |
| Series A as-converted | 5M × ($2.00 / $1.615) | ~6.2M shares (vs 10M under full ratchet) |
The difference is the whole ballgame: ~1.2M extra shares to Series A instead of 5M. Founders keep a fundable company; Series A gets meaningful but survivable protection. Note the levers founders can control: a larger broad base (bigger option pool counts in A) softens the adjustment, and raising more money at the down price worsens it (C grows) — model both before choosing the raise size, not after.
Narrow-based variant warning: if the charter counts only outstanding preferred/common (excluding the option pool) in A, the same round produces a harsher adjustment. Know which base your documents use — it changes the answer by 20–40% in typical cases.
Pay-to-Play: Protection for Participants Only
Pay-to-play provisions condition anti-dilution protection on showing up:
- Typical structure: investors who buy at least their pro rata in the down round keep full weighted-average protection; non-participants lose it entirely (their shares may even forcibly convert to common stock).
- Why companies demand it: it stops free-riding — no investor coasts on others’ rescue capital while keeping downside protection.
- Why funds hate it: a fund at the end of its reserves period may be unable to participate and gets punished for illiquidity, not disloyalty.
- Negotiation reality: pay-to-play is usually introduced in the down round (requiring a charter amendment and often a majority vote of the affected class voting to strip their own protection — itself a fiduciary flashpoint, see below).
Model the cap table both ways before the vote: participation scenarios change ownership, control provisions tied to preferred thresholds, and board composition. Run the scenarios in Cap Table tooling with counsel, not spreadsheets, and lock the version the board approves.
Repricing Underwater Options (Accounting + Tax)
After a down round, employee strike prices routinely sit far above fair market value. Repricing (lowering strikes) or exchanging underwater options restores incentives — but triggers real accounting:
- Modification accounting under ASC 718: measure incremental fair value (post-modification value minus pre-modification value) and recognize it over the remaining service period, on top of the original grant-date value still being amortized. See ASC 718 Guide for the full mechanics.
- 409A re-testing: the new strike must still equal or exceed current FMV, or discounted-option penalties apply. Get a fresh valuation dated to the repricing, not a memo referencing the old one — see 409A Valuations.
- Tender/exchange offers add securities complexity (including potential tender-offer rules for broad programs) — structure with counsel, and communicate tax consequences to employees in writing: ISOs can lose ISO status on modification, and 83(b) considerations may restart depending on structure.
Never reprice quietly between board meetings. Board approval with a documented business purpose, independent valuation, and cap-table impact analysis is the minimum file — auditors and future acquirers both ask for it, and an undocumented repricing reads as self-dealing.
Board Duties When Every Choice Dilutes Someone
Down rounds concentrate fiduciary risk because every structure choice moves value between classes:
- Loyalty runs to the corporation and all stockholders — but common stockholders, who absorb most dilution with no protection, deserve explicit consideration in the minutes. Courts have punished boards that treated preferred interests as the only interests that matter.
- Disinterested decision-making: directors affiliated with participating funds face classic conflict exposure. Use independent directors, a disinterested committee where available, independent financial advice, and a record showing alternatives considered (bridge vs priced round, pay-to-play vs straight terms).
- Entire-fairness readiness: conflicted transactions invite the strictest judicial review — fair dealing and fair price, documented contemporaneously, not reconstructed in litigation.
- Disclosure to stockholders: written consents and information statements must describe the dilutive impact accurately. Rosy “recapitalization” language that obscures a 50%+ common wipeout invites claims later.
- Minutes as the defense file: record the alternatives weighed, the advice relied on, the dissent expressed, and the common-stockholder analysis — see Board Minutes standards. The meeting where the board approved the down round with three lines of minutes is a litigation exhibit, not governance.
Coordinate with Audit Committee oversight where fairness opinions or independent valuations are commissioned, and keep the full record — term sheets, models, counsel memos, valuations — in a single diligence-ready file.
FAQ
Should founders ever accept full ratchet?
Almost never voluntarily — and never in a bridge without modeling the conversion math first. If a lender or bridge investor insists, quantify the fully-diluted outcome and negotiate caps, weighted-average fallbacks, or pay-to-play alternatives before signing.
Does a down round trigger anything besides anti-dilution?
Often: pay-to-play tripwires, option-pool top-up requirements, covenant breaches in venture debt, QSBS and 409A re-testing needs, and employee retention risk as option value evaporates — address all five in the same board session, not sequentially.
Next Steps
- Pull your charter’s exact anti-dilution formula (broad vs narrow base) and model this round’s math before the term sheet is signed — both full-ratchet and weighted-average scenarios.
- Run the board process as if it will be reviewed: independent voices, documented alternatives, explicit common-stockholder analysis, and counsel in the room.
- Reprice underwater options (if at all) with fresh valuations, ASC 718 modification accounting, and written employee tax communication — in that order.